7 Money Habits Keeping You Poor
folder_openMoney
commentNo Comments
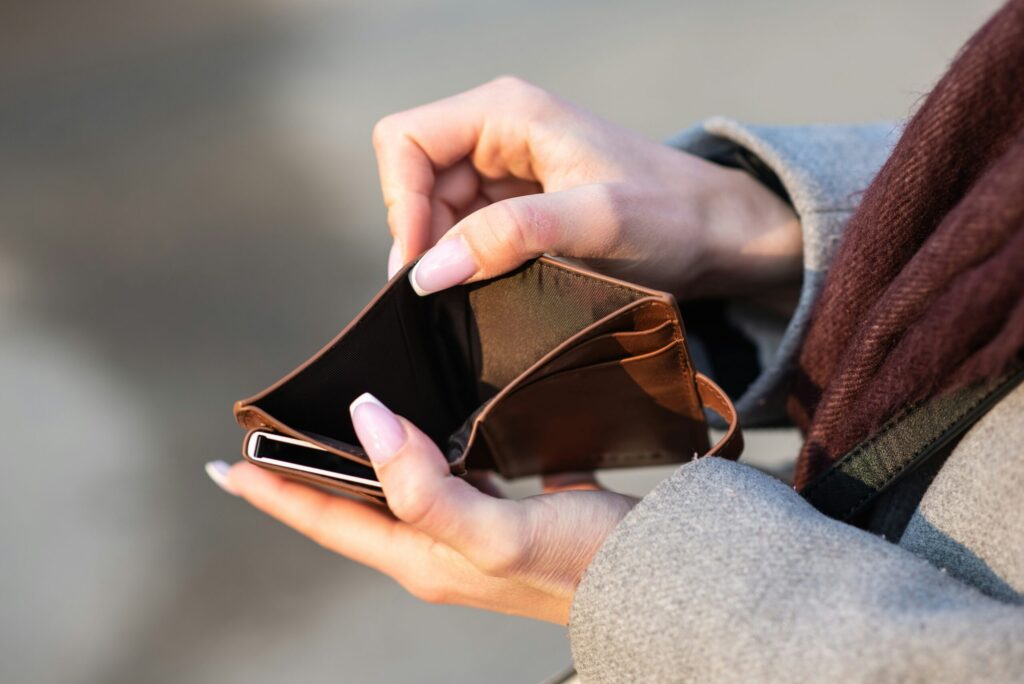
Have you ever wondered why despite your best efforts, you find yourself constantly struggling to make ends meet and can’t account or explain where the money went? Managing money effectively is crucial for securing a stable financial future. However, certain habits can unknowingly keep us trapped in a cycle of financial struggle.
Here are 7 money habits that may be keeping you poor, along with practical solutions to overcome them:
Burying Your Head in the Sand
Perhaps the most detrimental habit of all is ignoring your financial situation altogether, hoping that problems will magically resolve themselves. Avoiding financial responsibilities, such as paying bills on time, confronting debt, or planning for the future, can lead to a downward spiral of financial distress and missed opportunities.
Take ownership of your financial situation by facing it head-on and committing to proactive financial management. Create a realistic action plan to address outstanding debts, improve your budgeting skills, and work towards your long-term financial goals. Remember that seeking support from trusted friends, family members, or financial professionals is a sign of strength, not weakness.
Paying Yourself Last
One prevalent habit among individuals struggling financially is prioritising others’ needs over their own. While it’s noble to support loved ones and contribute to community causes, neglecting your financial well-being can hinder your long-term prosperity. For instance, constantly lending money to friends or family without setting aside savings for yourself can lead to financial stress and insecurity.
Start by establishing a budget that includes a dedicated portion for savings and personal expenses. Set boundaries and communicate openly with friends and family about your financial limitations. Remember, prioritising your financial health doesn’t mean neglecting others, it simply ensures that you’re in a better position to help them in the future.
Lack of Financial Awareness
Not having a clear understanding of your income and expenses can significantly hinder your ability to make informed financial decisions. Ignoring your financial reality may lead to overspending, missed opportunities for saving, and difficulty planning for the future.
Take the time to track your income and expenses diligently using tools like Quicken or spreadsheets. Identify areas where you can cut back on discretionary spending and allocate more resources towards savings and debt repayment. Regularly review your financial statements and adjust your budget as needed to stay on track.
Consumer Debt
Another detrimental habit is relying heavily on consumer debt to fund lifestyle expenses. Credit cards, payday loans, and other forms of high-interest debt can quickly spiral out of control, resulting in a cycle of debt repayment that drains your finances.
Take proactive steps to eliminate existing bad debt by prioritising high-interest balances and exploring debt consolidation options. Adopt a cash-first mentality and strive to pay for purchases with cash or debit whenever possible. Additionally, consider seeking professional financial guidance to develop a repayment plan tailored to your specific situation.
Unnecessary Spending
Mindless spending on non-essential items is a habit that can drain your finances without providing any lasting satisfaction or value. Whether it’s dining out frequently, splurging on designer clothes, or indulging in impulse purchases, overspending will sabotage your financial goals.
Practice mindful spending by distinguishing between needs and wants and prioritising purchases that align with your values and long-term objectives. Before making a discretionary purchase, pause and ask yourself whether it’s essential and whether you can afford it without jeopardising your financial stability. Consider implementing a waiting period for non-essential purchases to curb impulse buying.
No Emergency Fund
Failing to establish an emergency fund is a common mistake that can leave you vulnerable to unexpected expenses and financial emergencies. Without adequate savings to cover unforeseen costs, you may resort to borrowing or liquidating assets, further exacerbating your financial woes.
Make building an emergency fund a top priority, aiming to set aside 3 to 6 months’ worth of basic living expenses in a dedicated savings account. Start small if necessary, but consistently contribute to your emergency fund until it reaches the desired level. Treat it as a non-negotiable expense, just like paying bills or buying groceries.
Saving Without Investing
While saving money is essential for building a financial safety net, relying solely on traditional savings accounts may limit your wealth-building potential. Without the opportunity for growth through investments, your savings may struggle to keep pace with inflation, ultimately eroding their purchasing power over time.
Explore investment opportunities suited to your risk tolerance and financial goals, such as stocks ans shares, crypto, or real estate. Educate yourself about the basics of investing and consider seeking guidance from a qualified financial advisor to develop a diversified investment strategy. Remember to review your portfolio regularly and adjust your investments as needed to adapt to changing market conditions.
Breaking free from the cycle of financial struggle requires identifying and addressing detrimental money habits that may be holding you back. By acknowledging these habits and implementing practical solutions, you can take control of your finances and pave the way for a brighter financial future. Remember, small changes can yield significant results over time, so start today and commit to building healthy money habits that empower you to thrive.
Personal Budget Calculator
Check out our resources on personal finances below:



SHOP
-
 ELEVATE Purple Backpack
£40.00
-
 ELEVATE Cap
£22.00
-
 ELEVATE Black Drawstring Bag
£35.00